Strata Insurance
The policy an owners corporation inherits at handover is only as good as the building behind it — and the broker who can prove it. Strata insurance is compulsory for every strata-titled building in Australia, covering the building structure, common property and the liability that comes with shared ownership. What it costs, and how far it extends, depends on what the insurer knows about the building. On a new development that is usually very little — unless someone has been documenting it since construction.
Coverage Highlights
-
 Civil liability for advice, design, or certification decisions
-
 Claims-made cover, responds years after the work
-
Defence costs for regulatory or disciplinary inquiries
-
Reviewed against a widening duty of care
Building and common property cover, compulsory from registration
Compulsory cover
 The building and common property, including shared equipment, furniture, and fittings
- Public liability for injury occurring on common property
- Loss of rent or alternative accommodation following an insured event, where applicable
Optional cover
 Office bearers’ liability, for claims arising from wrongful acts by committee members
- Fidelity guarantee, for loss arising from misappropriation of owners corporation funds
- Personal accident cover for volunteers carrying out work on behalf of the owners corporation
- Mechanical and electrical breakdown cover
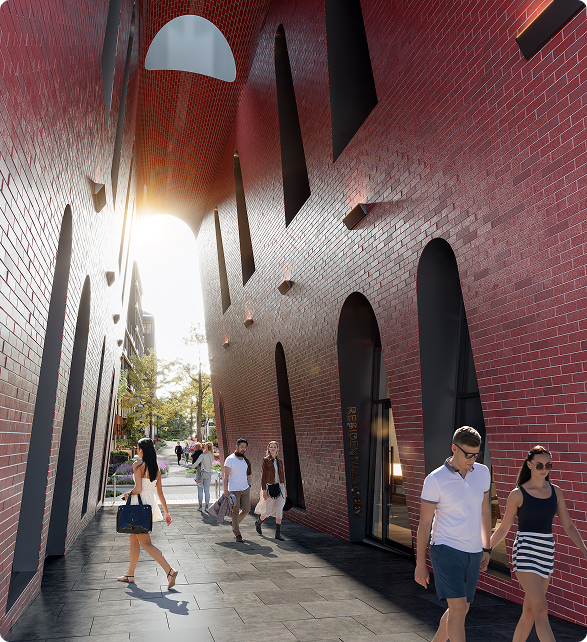
Handover is where strata cover gets set up right
A newly registered owners corporation places its first strata policy at the moment it knows least about the building. Latent Defects Insurance changes that. LDI is only issued after an independent Technical Inspection Service has reviewed the design and inspected the works at every stage gate — so the insurer is not pricing an unknown, it is pricing a building that has been independently verified through construction. The LDI then runs alongside the strata policy for ten years, meeting structural defects without the owners corporation having to prove anyone was at fault.
Underwriters price both facts. We have placed strata cover on LDI-backed buildings at 15 - 35% below standard rates, with extensions the open market does not offer as standard.
Continuity from developer to owners corporation
Another broker can quote a strata policy. They cannot evidence the building. Where SHC has arranged the development’s Latent Defects and contract works cover, we hold the inspection reports, the design reviews and the construction record — and we put that file in front of underwriters at handover. That evidence is what converts a well-built building into a lower premium and wider cover. Without it, the owners corporation is quoted like every other new building on the market. Developers using the full SHC ecosystem carry that advantage from feasibility through to the owners corporation — and hand over a building that is cheaper to insure because of how it was built, inspected and documented.
Get covered with confidence
Book a no-obligation scoping call with a construction insurance specialist. We’ll look at your project or program and recommend the right structure from the start.