Professional Indemnity Insurance
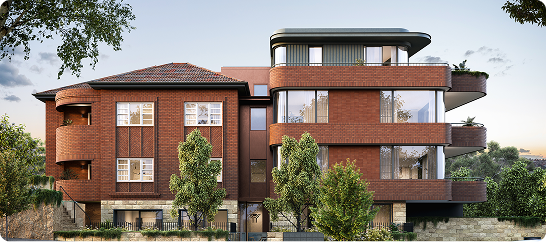
A design decision made today can become a claim a decade from now. Contract works insures the asset. Public liability insures the people and property around it. Professional indemnity insures the decisions — and in construction, the decisions outlive both.
Coverage Highlights
-
Civil liability for advice, design, or certification decisions
-
Claims-made cover, responds years after the work
-
Defence costs for regulatory or disciplinary inquiries
-
Reviewed against a widening duty of care
Frequently asked questions
Who needs professional indemnity insurance?
Anyone who provides professional advice, design, or certification services for a fee, including architects, engineers, building certifiers, quantity surveyors, project managers, and building designers.
How long does professional indemnity exposure last after a project is finished?
Claims can be brought years after a project reaches completion, particularly where a defect or design issue only becomes apparent later. This is why continuous, uninterrupted cover matters more than a single project's policy term.
Can individuals be held personally liable, not just the firm?
In some jurisdictions, courts have found that individuals with substantive control over building work can owe a personal duty of care, separate from the liability of the company they work for. This has been most clearly tested in NSW under the Design and Building Practitioners Act.
What is the difference between professional indemnity and public liability?
Professional indemnity covers claims arising from your advice, design, or professional services. Public liability covers third-party injury or property damage arising from physical business activity. Most professional firms need both.
Does professional indemnity cover regulatory inquiries?
Yes, typically. Cover can extend to the cost of defending an inquiry by a regulatory or disciplinary body into your professional conduct, separate from a civil claim.
What happens if my firm stops operating? Does past work stay covered?
Professional indemnity is generally a claims-made policy, meaning cover needs to be in place at the time a claim is made, not just when the work was carried out. This makes run-off cover an important consideration when a firm changes structure or ceases trading.
Complete your cover
-
.png)
Home Warranty
Residential builders must hold statutory warranty cover before taking a deposit. Getting it wrong creates compliance exposure that can stop a project before it starts.
.png)
Talk to us
Bring us a project at feasibility or early design and we’ll run a structured risk and insurability review with your team. No obligation, no placement required — you keep the output either way.