Skip to content
Rectangle 3543

Contract Works Insurance

Your site is exposed from the day it opens, not from the day it's finished.

A half-built structure is the most exposed asset on your balance sheet. Contract works insurance is what turns a total loss into a delay instead of an insolvency event. We’ve been placing it on Australian construction projects since 1989.

Coverage Highlights

  • Group 40583 (1) Single project or annual program options
  • Group 40583 (1) Arranged by SHC either as an Annual Policy or Project Specific depending upon SI2Q and complexity.
  • Group 40583 (1) Physical loss or damage to the works, materials, and equipment
image

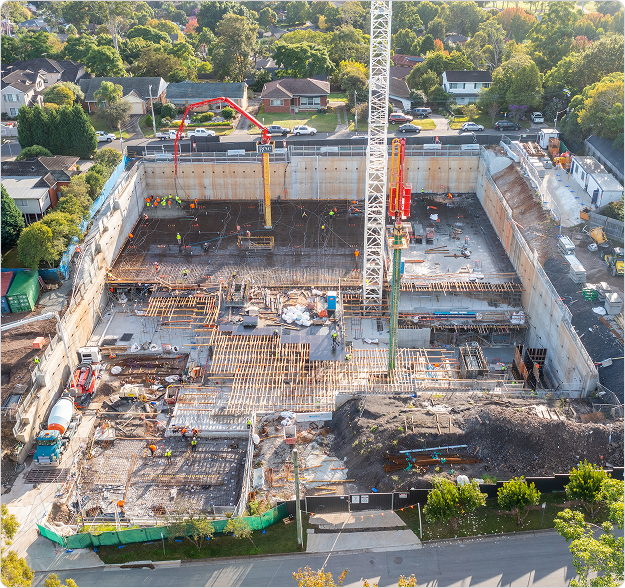
Protection from first works to practical completion

Until practical completion the works are an asset with no title, no occupancy, and a value that moves every month — sitting outside every operational property policy the project will eventually rely on. Contract works is the only instrument covering it.

Every contract allocates the risk of loss or damage to that asset; contract works insurance funds the allocation. The two are drafted separately, months apart, by different people — and the distance between them is where uninsured loss lives. What varies between programs is not the peril list. It is the definition of the insured works, the treatment of existing structures, the defect clause, the sub-limits, who can claim in their own name, and whether time is insured as well as damage.

Where the value sits

What is taken for granted in a Contract Works policy — works, materials, plant, reinstatement costs and third-party liability — is common ground. An excellent program can be decided by what sits around it.
  • Vector (1)

    Delay in start-up (ALOP / DSU) — the revenue and financing cost of finishing eight months late.

  • Vector (1)

    Escalation and variation — so the sum insured keeps pace with a contract that grows.

  • Vector (1)

    Defective works (LEG2 / LEG3, DE-series) — how much resulting damage the policy actually pays for, and how it ties into Latent Defects Insurance.

  • Vector (1)
    Existing structures — critical on refurbishment and adaptive reuse.
  • Vector (1)
    Marine cargo and cargo DSU — where major plant or façade systems are imported.

Where projects get caught out

A contract works dispute is rarely about whether there was a policy. It is about one of these.

  • Sum insured set at signature and never moved. Variations and escalation later, the declared value is short — and average reduces the whole claim, not just the shortfall.

  • Practical completion isn’t handover. Cover ceases at PC, the Property/Strata Insurance hasn’t incepted, and nobody has told the insurer. The gap can run for weeks.

  • The existing structure was never insured. On refurbishment the new works are covered and the building they’re attached to is not — or sits with a different insurer, excess and loss definition.

  • “Defects are excluded” — they aren’t under the right wording. Rectifying the defective work is excluded; resulting damage usually isn’t. The clause decides whether a failed pour costs you the slab or the structure above it.

  • Noted, but not insured. Noted interest doesn’t always confer a right to claim. A developer, financier or JV partner claiming in their own right needs named-insured status.

  • The annual policy didn’t meet the contract. Blanket contract works policies carry limits, project-value caps and construction-period caps. One project can breach all three.

  • Subcontractor works fell between policies. The head contract says the principal contractor insures everything; the subcontract says the sub does. Both assume the other.

  • Damage was covered; the delay wasn’t. The fire is paid in full. Eighteen months of holding costs and lost settlements are not — because ALOP was deferred at tender.

  • Sub-limits set the real cover. Debris removal, professional fees and authorities’ requirements are all capped. On a $200M project, a $2M debris removal sub-limit is not a rounding error.

Why developers insure Contract Works directly with SHC

We run this analysis before tender documents are issued. By the time the contract is executed, the advice is given and assists correct decision-making.

Principal-arranged

One program covering owner, financier, head contractor, subcontractors, consultants and suppliers.
  • One panel, one wording, one excess structure — no gaps between parties’ separate policies.
  • More competitive rates and extended covers. Leverage the LDI policy and its risk management. Consolidated buying power, cheaper than the sum of individual placements.
  • No cross-claims between insured parties, removing the most common source of dispute.
  • The principal controls limits, extensions and the claims process — and carries the administrative load.

Developer-arranged

The Developer insures the works and notes the builder’s and principal’s interests.
  • Simpler at tender stage; cover quality is set by the developer’s program.
  • Your recourse at claim time depends entirely on how the contract and policy were drafted.
  • Continued cover, not purchased multiple times, in the event of a builder insolvency.

What we do

One program, managed across the life of the project — from feasibility to final claim.

  • PHASE 1

    Before you commit

    Feasibility, design development and tender

    Project risk and opportunity workshops. What can go wrong, what it costs, what’s insurable, and what should be engineered out rather than insured.

    Insurance cost implications of design and methodology. Timber versus concrete, prefabrication, top-down construction, deep excavation beside existing structures — priced while the design can still change.

    Contract indemnity and insurance clause due diligence. What the contract obliges you to carry, what it leaves you exposed to, and what to redline — before execution.

    Due diligence on other parties’ insurances. A certificate of currency proves a policy existed on a date. We verify the cover behind it responds to your project.
  • PHASE 2

    Before you break ground

    Placement

    Project Risk Prospectus. An underwriting submission built so the market competes for the risk rather than pricing the unknown.

    Stakeholder briefing documentation. The program explained in the terms financiers, JV partners and boards each need.

    Negotiating value-for-money placement. Best total cost of risk across premium, retention, limits and exclusions — with extended coverage.

    Leverage Latent Defects Insurance. Apply the risk management from the TIS (Technical Inspection Service) and obtain lower rates due to the higher-quality asset.
  • PHASE 3

    On site and beyond

    Protection

    Claims and site risk protocols. Who notifies, in what timeframe, what evidence is preserved, who speaks to the loss adjuster — agreed before the first claim.

    Strategic claims management. Large construction claims are negotiations. We run them with the engineering, quantum and contractual argument prepared from day one.

Who should hold this policy?

  • Rectangle 3628

    Builders and head contractors

    Cover follows the works, not just your own trade. An active site carries risk from every subcontractor on it, and a properly structured policy reflects that.

  • Rectangle 3629

    Developers

    Control your own program. Contract works sits alongside your LDI program. LDI protects the completed building for ten years; contract works protects the build itself while it's underway. If the builder becomes insolvent, have the Contract Works Insurance in your own name and enjoy its benefits and continuity. 

Why SHC?

Frequently asked questions

What is the difference between contract works insurance and public liability insurance?

Contract works insurance protects the project itself, the building, materials, and equipment, against physical loss or damage during construction. Public liability protects you against claims from third parties injured or whose property is damaged because of your work. Most active sites need both.

Can contract works insurance be arranged for a single project?

Yes. Cover can be arranged for one project or as an annual policy covering every project you run, with premium based on works turnover across the year.

Does contract works insurance cover subcontractors?

Cover typically extends to subcontractor liability, product liability, and cross liability between parties on site, subject to policy terms.

What happens if there's a delay caused by an insured event?

Contract works insurance responds to physical loss or damage to the works. Delay-specific costs are generally a separate consideration and should be discussed directly with your broker when structuring the policy.

Does contract works cover work on an existing building?

Yes, as an optional extension. Renovations, alterations, and work on or near an existing structure can be covered for sudden and accidental damage during the construction process.

Who typically arranges this cover, the builder or the developer?

Either party can hold the policy, and it is sometimes shared by agreement. The right structure depends on the contract between builder and developer, which we can help you work through.

Complete your cover

  • Vector

    Plant and Equipment

    High-value plant and mobile equipment is often under-insured, particularly across multiple sites or when hired out.

  • Vector (1)

    Commercial Motor

    Fleet and vehicle risk is often fragmented across generalist insurers, with gaps in site-based and between-site use.
Your next project deserves certainty

Book a no-obligation scoping call and get advice from an LDI specialist. 
We’ll listen to your requirements and give you a clear recommendation from the start.